Form D: What Is It and Why Does It Matter?
Form D is a filing with the SEC required for most Regulation D offerings, providing transparency about private capital raises.
Form D is a filing with the SEC that companies must submit after selling securities in a private placement under Regulation D. Often called a "notice of sale of securities," Form D provides transparency into private capital markets by disclosing basic information about private offerings to investors and the general public.
What Is Form D?
Form D is not a registration statement but a short notice filing that issuers make with the SEC within 15 calendar days after the first sale of securities in an offering under Regulation D. The first sale is the date the first investor is irrevocably committed to invest, which can precede the closing or the transfer of funds. The SEC does not review or approve the offering; the form is simply a public record that a private placement is under way and who is behind it.
Purpose of Form D
- Regulatory Compliance: Required filing for most Regulation D offerings
- Market Transparency: The only public, standardized record of most private raises
- Investor Protection: Names the people running the issuer and anyone paid to sell
- Data Collection: Lets the SEC and states see the size and shape of the private market
When Form D Is Required
Issuers file Form D when they sell securities under:
- Rule 504 (up to $10 million in 12 months)
- Rule 506(b) (unlimited amount, no general solicitation, up to 35 non-accredited investors)
- Rule 506(c) (unlimited amount, general solicitation allowed, all purchasers must be verified accredited investors)
- Section 4(a)(5) (sales solely to accredited investors, up to $5 million)
Information Required on Form D
Form D is organized into 16 numbered items. Most of them are check boxes, but a handful carry most of the information a reader can actually use.
Issuer Information (Items 1, 2, 4 and 5)
- Identity and Contact: Legal name, any prior names, principal place of business and phone number
- Entity Type and Jurisdiction: Corporation, LLC, limited partnership, etc., and where it was organized
- Year of Incorporation: Whether the entity is over five years old, within the last five years (with the year), or yet to be formed
- Industry Group: A fixed list of categories; pooled investment funds also mark whether they are a hedge fund, private equity fund, venture capital fund or other fund
- Issuer Size: A revenue range for operating companies or a net asset value range for funds, though many issuers check "decline to disclose"
Related Persons (Item 3)
Item 3 lists every executive officer, director and promoter of the issuer, with a business address and relationship. For a fund, the related persons are typically the general partner or managing member and its executives, so Item 3 is often the clearest public link between a fund vehicle and the firm and people that run it. Reading Item 3 across many filings shows which individuals sit behind which companies and funds, and how often they raise.
Offering Information (Items 6 through 11)
- Exemption Claimed (Item 6): Rule 504, 506(b), 506(c), Section 4(a)(5), and, for funds, the Investment Company Act exclusion relied on, such as 3(c)(1) or 3(c)(7)
- Type of Filing (Item 7): New notice or amendment, and the date of first sale
- Duration (Item 8): Whether the offering is expected to last more than one year
- Type of Securities (Item 9): Equity, debt, options or warrants, pooled investment fund interests, and so on
- Business Combination (Item 10): Whether the offering is part of a merger or acquisition
- Minimum Investment (Item 11): The smallest investment accepted from an outside investor
Sales Compensation (Item 12)
Item 12 names each person paid commissions or similar compensation for selling the offering, with the recipient's CRD number, the associated broker-dealer and the states where they solicited. It is the public record of which placement agents and broker-dealers work on which raises. A blank Item 12 means the issuer sold directly, without paid intermediaries.
Amounts, Investors and Fees (Items 13 through 16)
- Offering and Sales Amounts (Item 13): Total offering amount (or "indefinite"), total amount sold so far, and the remainder. Comparing amount sold with the target shows how far along a raise is.
- Investors (Item 14): The total number of investors who have already invested, and how many of them are not accredited. A small count with a large amount sold points to a few institutional checks; a large count suggests a broad syndicate or platform raise.
- Sales Commissions and Finders' Fees (Item 15): Dollar amounts paid or estimated
- Use of Proceeds (Item 16): The amount of gross proceeds paid or to be paid to the executive officers, directors and promoters named in Item 3
Form D does not include financial statements, valuation, the price per share or a description of the business. Those live in the offering documents, if anywhere.
Filing Requirements and Deadlines
Initial Filing
- Deadline: Within 15 calendar days after the first sale (the next business day if that falls on a weekend or holiday). Filing before the first sale is permitted.
- Method: Online through the SEC's EDGAR system, which requires EDGAR access credentials
- Fee: No SEC filing fee
- Public Availability: Public on EDGAR as soon as it is accepted
Amendment Requirements
An issuer must file an amendment:
- To Correct Errors: As soon as practicable after discovering a material mistake of fact or error in the previous filing
- To Reflect Changes: When information changes, except for certain items such as the amount sold, the number of investors, issuer size, or an increase in the offering amount of 10% or less
- Annually: On or before the anniversary of the most recent filing, if the offering is still continuing
There is no requirement to file when an offering closes, so an amendment history tells you a raise ran past a year or that its terms changed, not that it finished.
Multiple Offerings
- Separate Forms: Each offering requires its own Form D
- Series and Parallel Funds: Each series or parallel vehicle usually files separately
- Continuous Offerings: Open-ended funds keep one notice alive with annual amendments
State Filing Requirements
Blue Sky Law Compliance
Securities sold under Rule 506 are "covered securities," so states cannot require registration or review the merits, but under blue sky laws they can require a notice filing:
- Notice Filing: Usually a copy of the federal Form D, filed through NASAA's Electronic Filing Depository in most states
- Filing Fees: Set by each state and sometimes scaled to the amount sold in that state
- Consent to Service: Some states require a consent to service of process
- Renewal Requirements: Some states require annual renewals for continuing offerings
Common State Variations
- Deadlines: Most states follow the federal 15-day window, but a few have their own timing
- Fees: Range from nothing to several hundred dollars or more per state
- Rule 504 Offerings: Not covered securities, so they may require state registration or qualification, not just a notice
Common Filing Errors and How to Avoid Them
Timing Errors
- Late Filing: Missing the 15-day deadline after first sale
- Wrong First-Sale Date: Counting from the closing instead of the date the first investor irrevocably committed
- State Deadline Confusion: Not understanding different state requirements
Information Errors
- Incorrect Exemption: Claiming wrong Regulation D rule
- Missing Related Persons: Leaving out executive officers, directors or promoters in Item 3
- Wrong Address Information: Using incorrect business addresses
- Sales Data Errors: Incorrect amounts sold, investor counts, or sales compensation recipients
Technical Errors
- EDGAR Access: Obtaining EDGAR access codes takes time; start before the first sale
- Format Problems: Incorrect formatting of required information
- Access Code Issues: Problems with EDGAR access credentials
Consequences of Non-Compliance
SEC Enforcement
- Warning Letters: SEC may send deficiency letters
- Enforcement Actions: Cease and desist orders or penalties
- Disqualification: Failing to file does not by itself void the exemption, but under Rule 507 an issuer enjoined by a court for not filing loses the use of Regulation D going forward
- Ongoing Scrutiny: Increased regulatory attention
State Consequences
- State Enforcement: State securities regulators may take action
- Penalties and Fines: Financial penalties for non-compliance
- Business Restrictions: Inability to conduct future offerings
- Consent Orders: Required compliance agreements
Practical Consequences
- Due Diligence Red Flags: Creates issues for future transactions
- Audit Findings: May surface during financial audits
- Legal Costs: Expense of addressing compliance failures
- Reputation Risk: Public record of non-compliance
Using Form D Data
For Investors
- Market Research: See which companies and funds are raising, how much, and under which exemption
- Due Diligence: Check a company's stated fundraising history against its filed amounts sold and dates of first sale
- People Behind the Raise: Use Item 3 to see who runs an issuer and what else they have raised
- Fund Tracking: Follow a manager's successive funds and how quickly each one fills
For Service Providers
- Business Development: Identify companies and funds that have just raised capital
- Intermediary Mapping: Use Item 12 to see which placement agents and broker-dealers work with which issuers
- Compliance Monitoring: Watch for annual amendments on continuing offerings
- Benchmarking: Compare raise sizes, minimums and investor counts across an industry group
For Researchers and Media
- Market Trends: Analyze private capital activity by industry, exemption and size
- Venture Activity: Startup rounds and venture fund closes usually appear as Form D filings
- Journalism: Report on private company fundraising from the primary source
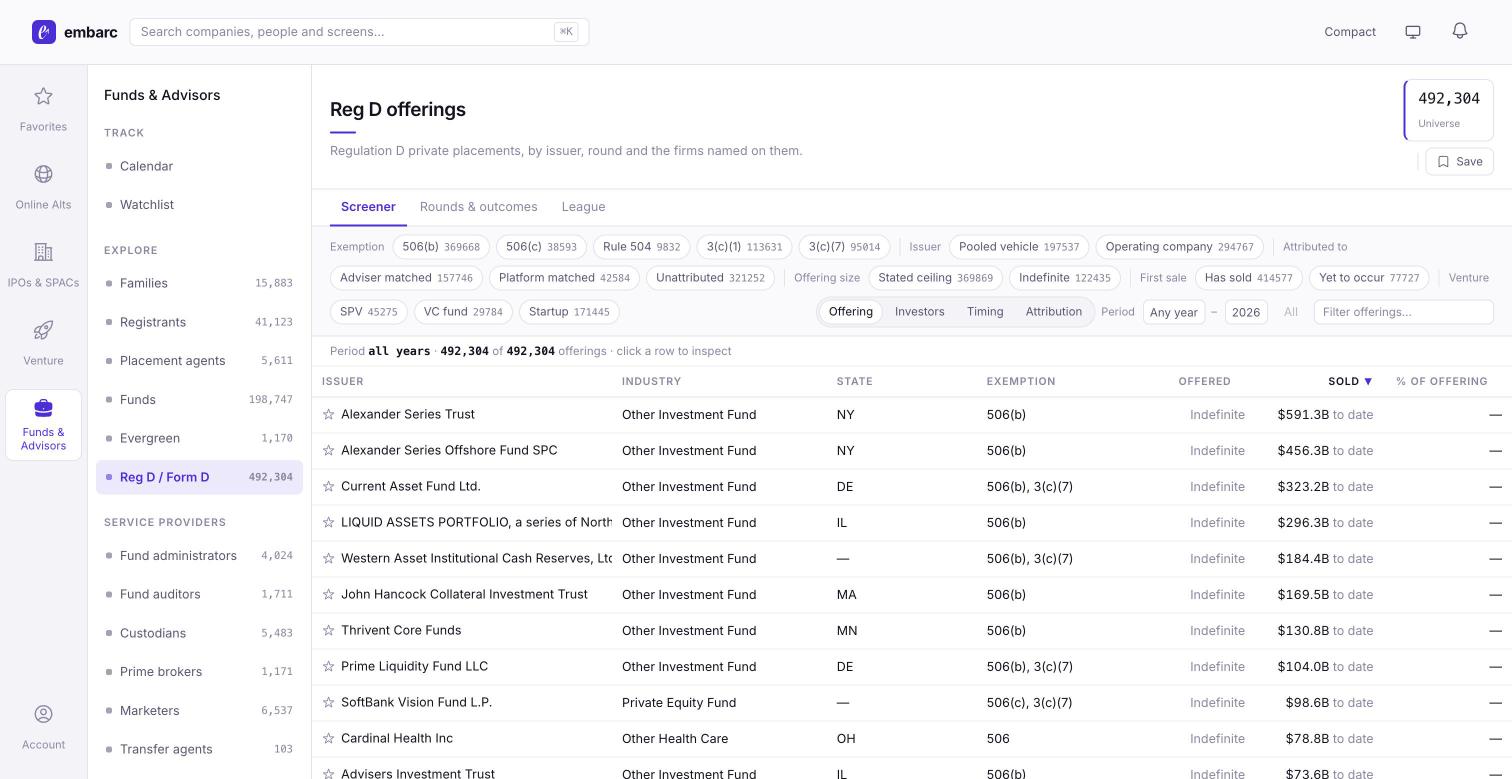
embarc parses every Form D into structured fields. In the embarc dashboard, the Reg D offerings screener filters filings by amount sold, exemption, industry and date; placement agents are built from Item 12; private funds combine Form D with Form ADV; and startup funding rounds come from operating companies' Form D filings.
Best Practices for Form D Compliance
Recommended Practices:
- Calendar Tracking: Set up deadline tracking systems
- Legal Counsel: Work with experienced securities attorneys
- State Research: Understand all applicable state requirements
- Record Keeping: Maintain detailed records of all sales
- Regular Reviews: Periodically review filings for accuracy
- Amendment Protocols: Have procedures for correcting errors
Technology and Automation
Filing
- EDGAR Online Form: The SEC's own web form for Form D, free to use
- Filing Agents: Law firms and commercial filing agents submit on the issuer's behalf
- State Notices: NASAA's Electronic Filing Depository handles most state notice filings and fees
Data Integration
- Structured Data: Every Form D is filed as XML, so the fields can be parsed and compared across filings
- Deadline Tracking: Track the 15-day initial deadline and annual amendment dates
Conclusion
Form D filing is a critical compliance requirement for private offerings under Regulation D. While the form itself is relatively straightforward, the consequences of non-compliance can be significant. Companies conducting private placements should establish robust procedures to ensure timely and accurate filing of Form D at both federal and state levels.
Beyond compliance, Form D is the most complete public record of private capital raising: who raised, how much, from how many investors, and who was paid to sell it.
Explore the Data
The table below shows this week's largest Form D raises. For more:
- Reg D offerings screener (embarc dashboard)
- Placement agents named in Item 12
- Regulation D and Form D guide
This week's largest Form D raises
New Form D offerings first filed in the past 7 days, by the amount the issuer reports sold.
| Issuer | Kind | First filed | Amount sold |
|---|---|---|---|
| Ramp Business Corp | KindOther Technology | First filed2026-10-16 | Amount sold$1.6B |
| UPS Multi-Strategy Hedge Fund Ltd | KindFund · Other Investment Fund | First filed2026-10-14 | Amount sold$1.3B |
| Maverick Silicon Fund II, L.P. | KindFund · Private Equity Fund | First filed2026-10-16 | Amount sold$1.1B |
| Mason Wells Buyout Fund VI, LP | KindFund · Private Equity Fund | First filed2026-10-13 | Amount sold$833M |
| AQR Flex 1 Series LLC - Series F79 | KindFund · Hedge Fund | First filed2026-10-15 | Amount sold$549M |
| PEG Global Private Equity XIII (Holding) L.P. | KindFund · Private Equity Fund | First filed2026-10-14 | Amount sold$518M |
| Pce LLC | KindFund · Hedge Fund | First filed2026-10-16 | Amount sold$457M |
| Taurus Co-Invest, SCSp | KindFund · Other Investment Fund | First filed2026-10-13 | Amount sold$364M |
| Heritage Holding Fund II, LP | KindFund · Private Equity Fund | First filed2026-10-13 | Amount sold$330M |
| PEG Global Private Equity XIII SCSp SICAV-RAIF | KindFund · Private Equity Fund | First filed2026-10-14 | Amount sold$287M |
Related Articles
Regulation D (Reg D) and Form D Filings
Regulation D provides exemptions that allow companies to raise capital privately. Form D is a notice companies file with the SEC after selling securities without registration.
SEC FormsPrivate MarketsPrivate Placements Explained
Private placements are investment offerings that are not sold through public markets, but directly to select investors. Discover how they work and what to watch for.
Private MarketsInvestor BasicsWho Qualifies as an Accredited Investor?
An accredited investor meets certain financial criteria, enabling access to private investment opportunities. See the requirements and what it means for your investment options.
Investor BasicsWhat is Due Diligence?
Due diligence is the research and verification process investors use to evaluate an opportunity before investing, including financials, legal compliance, and business risks.
Investor BasicsRisk