Regulation D (Reg D) and Form D Filings
Regulation D provides exemptions that allow companies to raise capital privately. Form D is a notice companies file with the SEC after selling securities without registration.
Regulation D provides critical exemptions from SEC registration requirements that allow companies to raise capital privately from investors. When companies conduct private placements under Regulation D, they file Form D with the SEC to give notice of the offering. Those notices are public, which makes Form D one of the best windows into private fundraising by startups, funds, and real estate sponsors.
What Is Regulation D?
Regulation D is a set of SEC rules that provides exemptions from the registration requirements of the Securities Act of 1933. These exemptions allow companies to offer and sell securities without going through the lengthy and expensive process of registering the securities with the SEC, making it much easier and cost-effective to raise capital privately.
Purpose and Benefits
- Cost Reduction: Eliminates expensive registration process for private offerings
- Time Efficiency: Allows faster access to capital markets
- Flexibility: Fewer disclosure requirements than public offerings
- Privacy: Less public disclosure of business information
- Accessibility: Makes private capital raising viable for smaller companies
The Three Main Exemptions
Regulation D contains three key rules that provide different exemptions:
- Rule 504: Small offerings up to $10 million
- Rule 506(b): Private placements, without general solicitation, to accredited and a limited number of sophisticated investors
- Rule 506(c): General solicitation allowed with verified accredited investors
Rule 505, a former $5 million exemption, was repealed in 2017.
Rule 504: Small Offerings
Basic Requirements
- Offering Limit: Maximum of $10 million in any 12-month period
- Investor Types: No federal limit on number or sophistication of investors
- Eligible Issuers: Not available to Exchange Act reporting companies, investment companies, or blank check companies
- General Solicitation: Generally prohibited, with state law exceptions
- Resale Restrictions: Securities are restricted unless the state law exceptions below apply
State Law Considerations
Unlike Rule 506 offerings, Rule 504 offerings are not preempted from state review, so they must be registered or exempt under the blue sky laws of each state where they are sold. General solicitation is permitted, and the securities are not restricted, if:
- The offering is registered in a state that requires a substantive disclosure document to be delivered to investors, or
- It relies on a state exemption that permits general solicitation for sales to accredited investors only
Typical Use Cases
- Small business capital raising
- Real estate investment opportunities
- Local investment clubs
- Early-stage startups with limited capital needs
Rule 506(b): Traditional Private Placements
Key Features
- Unlimited Offering Size: No limit on amount that can be raised
- Investor Limits: Unlimited accredited investors plus no more than 35 sophisticated non-accredited investors in any 90-day period
- No General Solicitation: Cannot publicly advertise the offering
- Pre-existing Relationships: Selling to people with whom the issuer or its agents had a substantive relationship before the offering is the usual way to show there was no general solicitation
Sophisticated Investor Requirements
Non-accredited investors in Rule 506(b) offerings must be "sophisticated," meaning they have:
- Sufficient knowledge and experience in financial matters
- Capability to evaluate the merits and risks of the investment
- Ability to bear the economic risk of the investment
Disclosure Requirements
Required Disclosures for Non-Accredited Investors
- Disclosure generally comparable to a registered offering, usually in a private placement memorandum
- Financial statements scaled to the size of the offering, audited in many cases
- Opportunity to ask questions and receive answers
- Access to additional information about the offering
Rule 506(c): General Solicitation Permitted
Key Differences from 506(b)
- General Solicitation Allowed: Can publicly advertise and market the offering
- Accredited Investors Only: All investors must be accredited
- Verification Required: Must take reasonable steps to verify accredited status
- No Pre-existing Relationship: Can sell to previously unknown investors
Verification Methods
Companies must verify that investors are accredited through methods such as:
- Income Verification: Tax returns, W-2s, or CPA letters for income-based qualification
- Net Worth Verification: Bank statements, brokerage statements, or third-party reports
- Professional Credentials: Series 7, 65, or 82 licenses for certain professionals
- Third-Party Verification: Written confirmation from a broker-dealer, registered investment adviser, attorney, or CPA
- High Minimum Investment: Under SEC staff guidance issued in 2025, a minimum investment of at least $200,000 for individuals or $1 million for entities, with written representations and no contrary information, can be a reasonable verification step
Marketing Considerations
General Solicitation Guidelines
- Can use websites, social media, and advertising
- Must still comply with anti-fraud provisions
- Should include appropriate disclaimers
- Must verify accredited status before accepting investment
Form D: Notice of Exempt Offering
What Is Form D?
Form D is a brief notice filing that companies must submit to the SEC when they sell securities under Regulation D exemptions. It's not an application for approval but rather a notification that an offering has taken place. For a field-by-field walkthrough, see Form D explained.
Filing Requirements
- Timing: Must be filed no later than 15 calendar days after the first sale of securities
- Amendments: Must be amended at least annually while the offering continues, and to correct material mistakes or reflect most changes in the information
- No Closing Filing: There is no final notice when an offering ends; the amendments simply stop
- Electronic Filing: Must be filed electronically through the SEC's EDGAR system
Information Required
Form D Content
- Issuer Information: Company name, address, entity type, year of incorporation, industry group, and (optionally) a revenue or net asset value range
- Related Persons: Executive officers, directors, and promoters by name
- Offering Details: Type of securities, exemption claimed, date of first sale, and total offering amount (which funds often list as indefinite)
- Sales Information: Amount sold, amount remaining, minimum investment, and the number of investors, including any non-accredited ones
- Sales Compensation: Names of brokers or placement agents paid, and the commissions and finder's fees
- Use of Proceeds: Only the amount paid to officers, directors, and promoters, not a full use-of-proceeds breakdown
Public Access and Implications
- Public Database: Form D filings are publicly searchable on the SEC website
- Investment Research: Used by investors, competitors, and researchers
- Regulatory Oversight: The SEC does not review or approve Form D, but uses it in examinations and enforcement
- State Notifications: States do not get the SEC filing automatically; issuers make separate state notice filings, usually through NASAA's electronic filing system
Compliance and Legal Considerations
Federal Requirements
- Anti-Fraud Provisions: Must comply with federal anti-fraud rules regardless of exemption
- Integration Rules: Multiple offerings may be treated as one for exemption purposes; Rule 152, adopted in 2020, sets the framework and safe harbors
- Resale Restrictions: Securities are "restricted" and subject to resale limitations
- Bad Actor Disqualification: Certain individuals can disqualify offerings
State Law Compliance
- Blue Sky Laws: Must comply with state securities laws in each state where offered
- Notice Filings: Rule 506 securities are “covered securities,” so states can require only a notice filing (typically a copy of Form D) and a fee
- Rule 504 Offerings: Not preempted, so they face state registration or exemption and, in some states, merit review
- Anti-Fraud Authority: States keep their anti-fraud powers over all offerings
Common Compliance Mistakes
Pitfalls to Avoid
- Late or missing Form D filings
- Inadequate investor verification for 506(c)
- General solicitation in 506(b) offerings
- Insufficient disclosure to non-accredited investors
- Failure to comply with state law requirements
- Improper integration of multiple offerings
Best Practices for Issuers
Planning and Preparation
- Legal Counsel: Work with experienced securities attorneys
- Structure Selection: Choose appropriate Reg D exemption for your situation
- Documentation: Prepare comprehensive private placement memorandum
- State Law Review: Analyze requirements in all relevant states
Investor Relations
- Qualification Process: Implement systematic investor qualification procedures
- Disclosure Materials: Provide appropriate disclosure documents to investors
- Question Handling: Allow investors to ask questions and verify information
- Documentation: Maintain detailed records of all investor communications
Ongoing Compliance
- Filing Deadlines: Monitor and meet all filing deadlines
- Record Keeping: Maintain detailed records of the offering process
- Updates: File required amendments and final notices
- Resale Education: Educate investors about resale restrictions
For Investors: Understanding Reg D Investments
Key Considerations
- Accreditation Requirements: Understand if you qualify as an accredited investor
- Illiquidity Risk: Recognize that these investments typically cannot be easily sold
- Limited Information: Less disclosure than public offerings
- Due Diligence: Conduct thorough investigation of investment opportunity
Red Flags to Watch
- High-pressure sales tactics or rushed decisions
- Promises of guaranteed returns or "risk-free" investments
- Lack of proper documentation or disclosure materials
- Unregistered sales agents or unlicensed promoters
- General solicitation for supposed 506(b) offerings
Verification and Documentation
Investor Checklist
- Verify the exemption being used for the offering
- Review the issuer's Form D filings, including the related persons and sales compensation
- Understand resale restrictions and holding periods
- Assess the company's business model and financials
- Evaluate management team and their track record
- Consider the total investment in context of your portfolio
Conclusion
Regulation D and Form D filings form the backbone of private securities offerings in the United States. These exemptions enable companies to raise capital efficiently while providing important protections for investors. Understanding the requirements and implications of each exemption is crucial for both issuers and investors participating in private markets.
Success in Regulation D offerings requires careful attention to compliance requirements, proper documentation, and adherence to both federal and state securities laws. The differences between Rules 504, 506(b), and 506(c) can significantly impact an offering's structure and marketing approach.
For investors, Regulation D offerings can provide access to unique investment opportunities, but they require careful due diligence and understanding of the associated risks. The private nature of these offerings means less information may be available compared to public securities, making thorough investigation even more important. To compare Reg D with the public exempt routes, see Reg A vs. Reg D vs. Reg CF.
Explore the Data
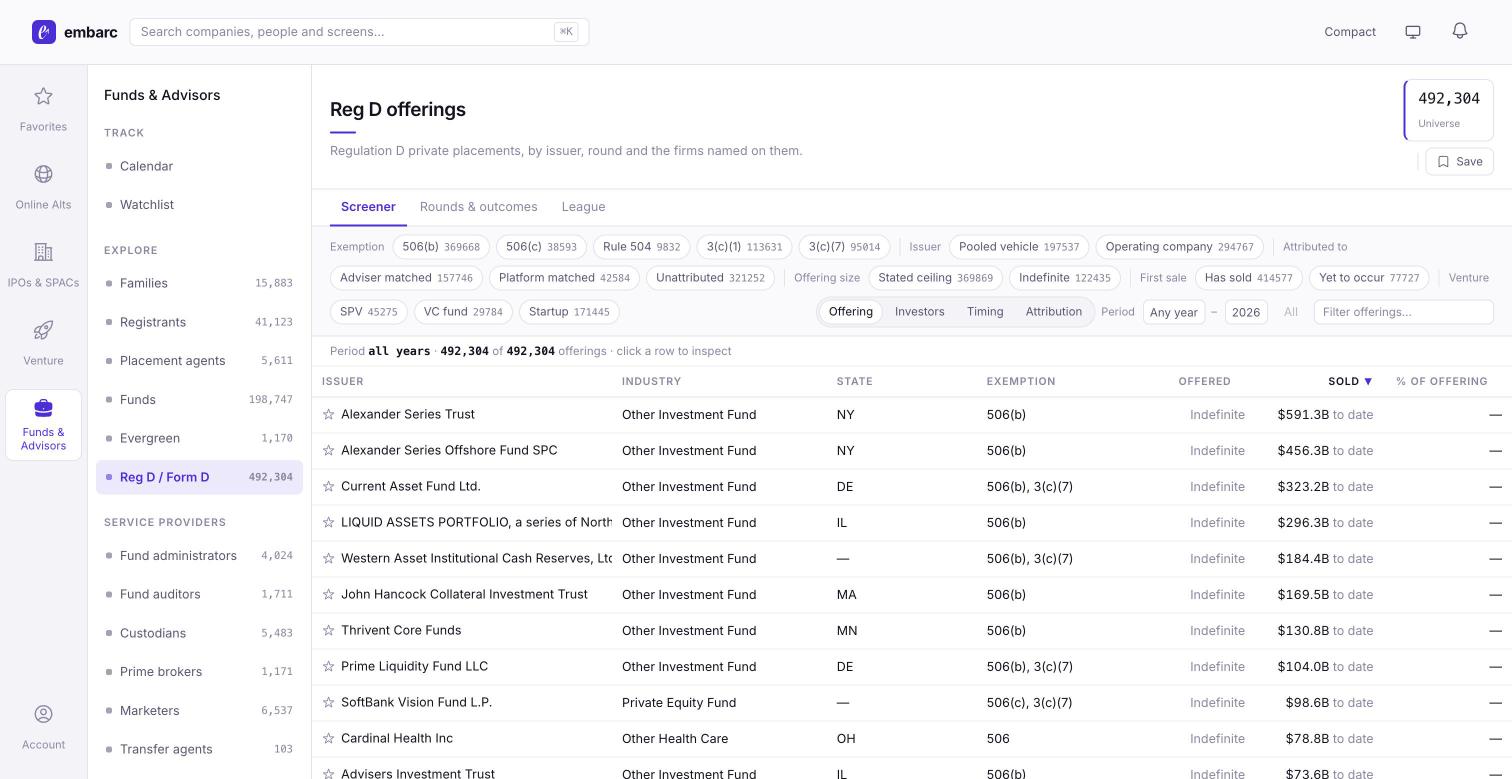
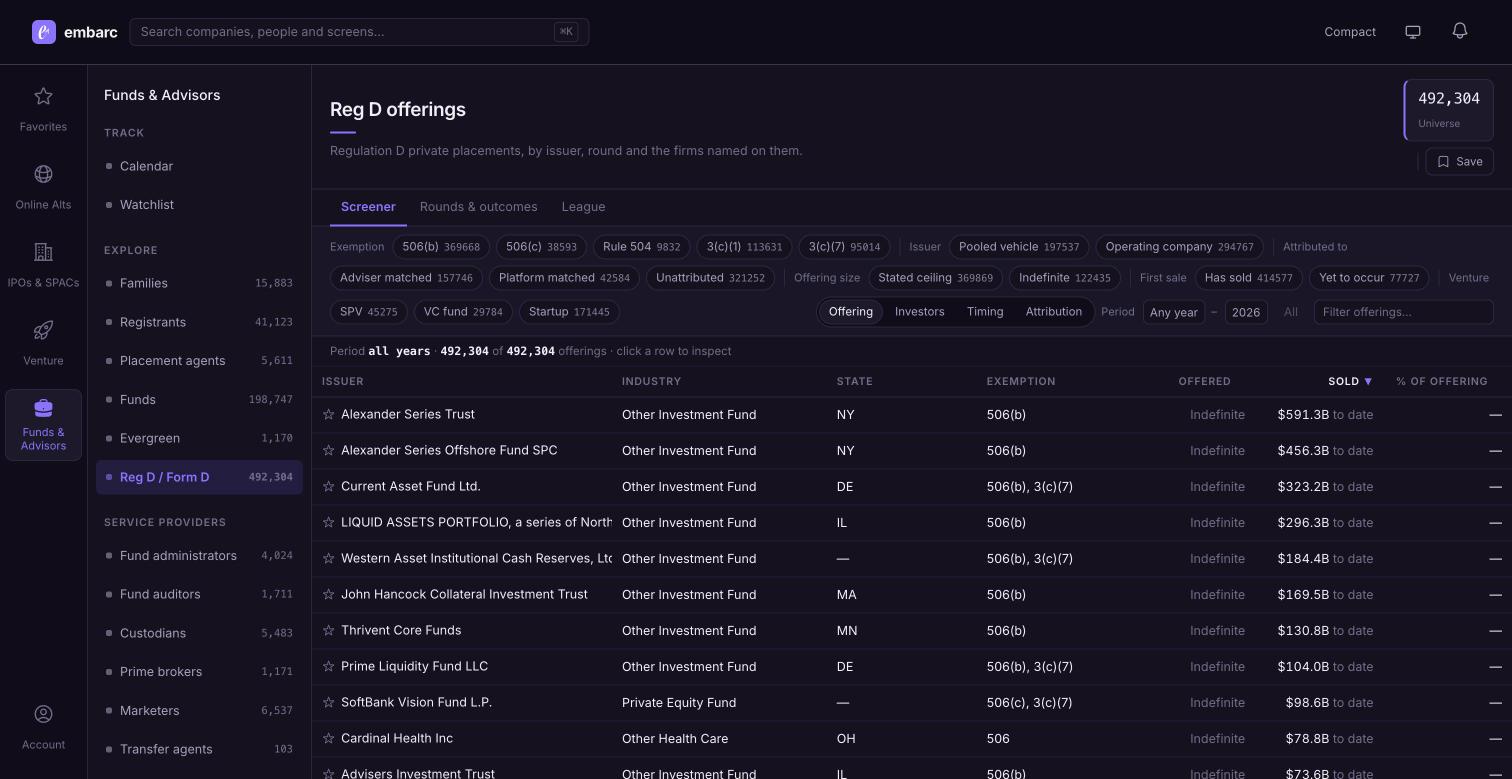
The table below shows this week's largest Form D raises. The full record is in the embarc dashboard:
- Form D offerings, by exemption, size, industry, and investor count
- Placement agents named in the sales compensation section
- Private funds that raise under Reg D
This week's largest Form D raises
New Form D offerings first filed in the past 7 days, by the amount the issuer reports sold.
| Issuer | Kind | First filed | Amount sold |
|---|---|---|---|
| Ramp Business Corp | KindOther Technology | First filed2026-10-16 | Amount sold$1.6B |
| UPS Multi-Strategy Hedge Fund Ltd | KindFund · Other Investment Fund | First filed2026-10-14 | Amount sold$1.3B |
| Maverick Silicon Fund II, L.P. | KindFund · Private Equity Fund | First filed2026-10-16 | Amount sold$1.1B |
| Mason Wells Buyout Fund VI, LP | KindFund · Private Equity Fund | First filed2026-10-13 | Amount sold$833M |
| AQR Flex 1 Series LLC - Series F79 | KindFund · Hedge Fund | First filed2026-10-15 | Amount sold$549M |
| PEG Global Private Equity XIII (Holding) L.P. | KindFund · Private Equity Fund | First filed2026-10-14 | Amount sold$518M |
| Pce LLC | KindFund · Hedge Fund | First filed2026-10-16 | Amount sold$457M |
| Taurus Co-Invest, SCSp | KindFund · Other Investment Fund | First filed2026-10-13 | Amount sold$364M |
| Heritage Holding Fund II, LP | KindFund · Private Equity Fund | First filed2026-10-13 | Amount sold$330M |
| PEG Global Private Equity XIII SCSp SICAV-RAIF | KindFund · Private Equity Fund | First filed2026-10-14 | Amount sold$287M |
Related Articles
Regulation A (Reg A, Reg A+) Explained
Regulation A, also called Reg A or Reg A+, is a way for companies to raise up to $75 million from both accredited and non-accredited investors, with fewer requirements than a full IPO.
SEC FormsCrowdfundingPrivate Placements Explained
Private placements are investment offerings that are not sold through public markets, but directly to select investors. Discover how they work and what to watch for.
Private MarketsInvestor BasicsWho Qualifies as an Accredited Investor?
An accredited investor meets certain financial criteria, enabling access to private investment opportunities. See the requirements and what it means for your investment options.
Investor BasicsWhat is Due Diligence?
Due diligence is the research and verification process investors use to evaluate an opportunity before investing, including financials, legal compliance, and business risks.
Investor BasicsRisk